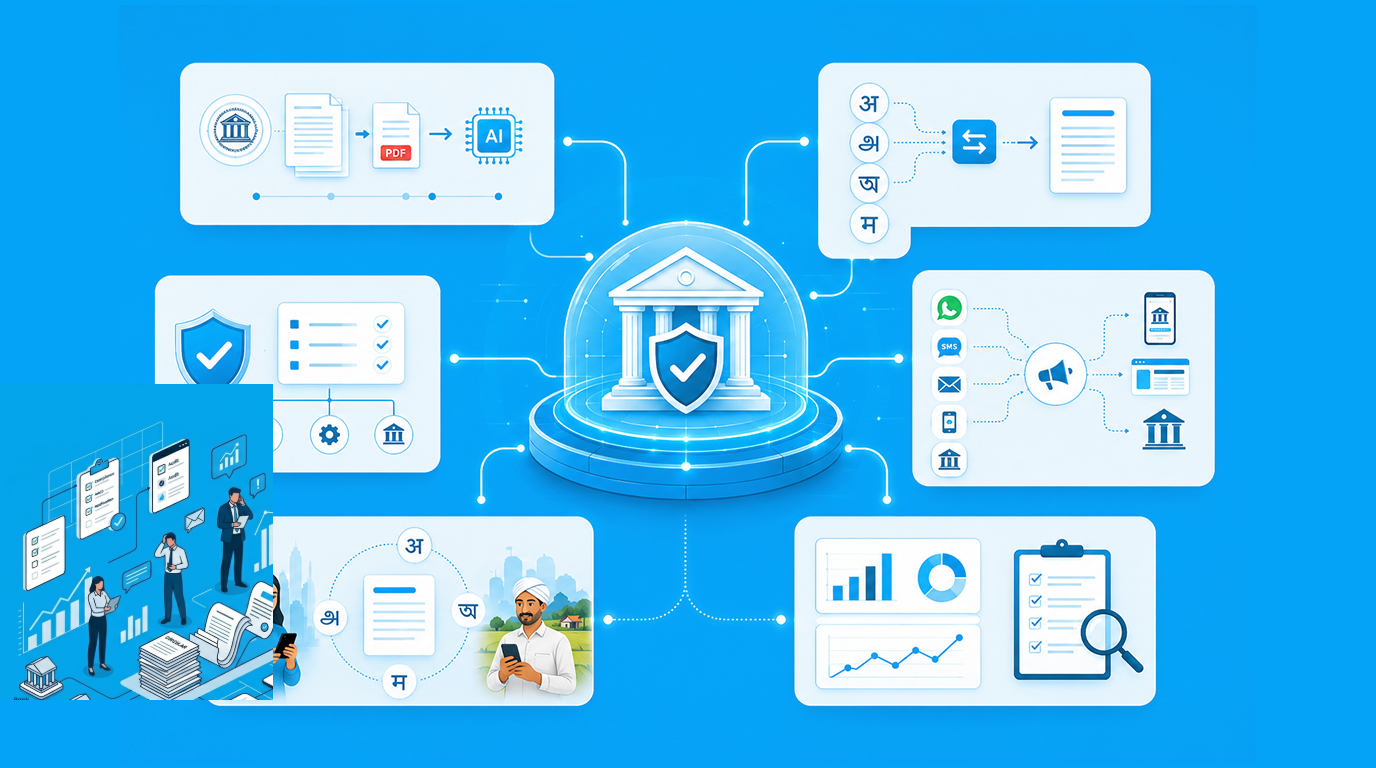
In India's financial sector, language is no longer just a customer experience problem. It has quietly become a compliance issue.
A borrower in Nashik raises a grievance in Marathi. A policyholder in Coimbatore submits a claim document in Tamil. A collections reminder reaches a customer in Hindi instead of English and suddenly gets a response that had stalled for weeks. These are operational moments, but they are also regulatory moments. And BFSI leaders are beginning to treat them that way.
For years, most institutions approached multilingual communication as a front-end layer. Translate the app. Localise the IVR. Add regional chatbot support. Done.
That model is breaking down.
Today, the pressure comes from multiple directions at once. RBI expectations around customer fairness are tightening. Increasingly SEBI-regulated workflows are demanding traceability. The servicing expectations driven by IRDAI are getting more digitally intensive. India's DPDP framework has also forced companies to re-evaluate how they transfer client data between systems, providers and languages.
The result is a bigger shift. Financial institutions are now building multilingual regulatory workflows instead of isolated translation experiences.
And that distinction matters more than most people realise.
Why multilingual compliance suddenly became an important topic
The old assumption was simple: English remained the operating language of compliance, while regional languages were primarily for acquisition or support.
But BFSI operating models in India have changed dramatically in the past five years.
Digital onboarding has expanded into Tier 2 and Tier 3 markets. Insurance penetration is moving deeper into semi-urban regions. Collections teams increasingly interact with customers more comfortably in local languages than in formal English. Even grievance escalation data shows a recurring pattern — customers respond faster and more accurately when communication happens in their preferred language.
That is where the economics start to change.
Several large institutions now report measurable operational improvements from multilingual servicing workflows, including nearly 25% faster grievance resolution cycles and 20–30% higher collections response rates when outreach is localised contextually rather than translated literally.
The keyword there is "contextually".
Most translation systems were never designed for regulated environments. They convert languages. They do not preserve intent, auditability, consent lineage, or policy consistency across workflows. In BFSI, that gap becomes risky rapidly.
According to McKinsey, generative AI adoption in customer care is increasingly focused on personalization, workflow acceleration, and operational efficiency rather than isolated chatbot deployments. The firms seeing value are embedding AI into end-to-end operational systems instead of using it as a surface-level feature. (McKinsey & Company)
That shift is visible across Indian banking and insurance as well.
The real problem is not translation. It is workflow fragmentation.
Many BFSI institutions already have multilingual assets somewhere in the organisation.
The issue is fragmentation.
A typical enterprise may use:
- One vendor for document translation
- Another for voice workflows
- Separate compliance systems
- Disconnected CRM records
- Manual escalation logs
- And partially digitized regional servicing processes
When regulators request audit visibility, stitching together that operational trail becomes painful.
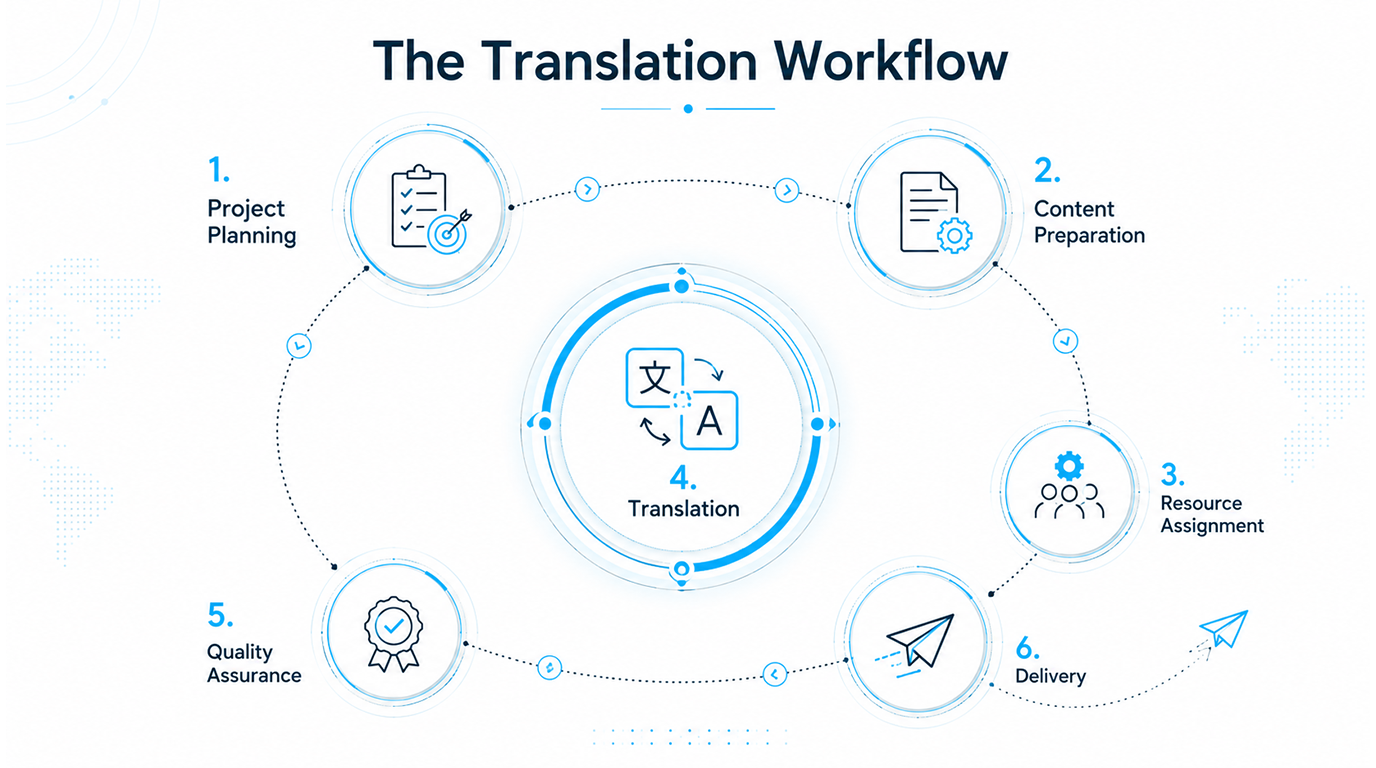
One compliance leader at a private sector lender described it bluntly during an industry roundtable last year: "We had translated communication everywhere but no unified compliance memory."
That phrase captures the current market reality almost perfectly.
Modern regulatory workflows now require:
- Traceable communication history
- Language consistency across channels
- Immutable audit logs
- Consent-aware processing
- Version-controlled document translation
- And explainable AI-assisted decisions
Without those foundations, multilingual operations create more risk instead of less.
This is why institutions are investing in infrastructure-level language systems rather than standalone translation utilities.
RBI-ready workflows are becoming infrastructure decisions
There is a noticeable change in how enterprise architects discuss language AI inside BFSI organizations.
Three years ago, the conversation was mostly around automation.
Now it is around governance.
Institutions want systems that can:
- Maintain audit trails automatically
- Preserve source-to-target translation lineage
- Support regulator review
- Enforce role-based access controls
- And align with DPDP-oriented data handling requirements
That last point is especially important.
India's digital personal data protection framework has fundamentally altered how enterprises think about data movement and processing. Financial institutions are now expected to demonstrate not only security but also accountability and explainability around customer data operations.
Deloitte India notes that DPDP readiness requires ongoing governance measures, proactive compliance monitoring, and clear operational controls around digital personal data processing. (Deloitte)
That has direct implications for multilingual BFSI workflows because translated communication often contains sensitive customer information, financial records, KYC data, or grievance documentation.
In practical terms, this means institutions increasingly prefer the following:
- On-prem or controlled-cloud deployments
- Regional data residency controls
- Human-in-the-loop review models
- Encryption-backed document pipelines
- And tamper-resistant workflow logging
This scenario is where immutable audit logs are becoming strategically important.
Not because they sound sophisticated in vendor presentations. But because regulated institutions need defensible operational histories when disputes arise.
Document translation is now tied to risk operations
One of the most significant changes happening quietly inside BFSI is the repositioning of document translation from a support function into a risk-control layer.
Historically, translated documents were often treated as customer convenience outputs. Today they increasingly influence the following:
- Claims processing
- Collections negotiations
- Lending disclosures
- Grievance escalations
- Legal notices
- Onboarding verification
- And regulatory correspondence
A mistranslated clause is no longer just a service issue. It can become a compliance issue.
That is why institutions are moving toward centralised multilingual workflow engines where translation memory, approval chains, legal templates, and audit records operate together instead of separately.
In collections specifically, the impact has been surprisingly strong.
McKinsey's research on AI-enabled credit customer assistance highlights how generative AI is reshaping customer support and collections operations through personalised engagement and workflow augmentation. (McKinsey & Company)
Indian BFSI teams are seeing this firsthand.
Collections response rates enhance when the communication sounds locally natural, rather than officially translated. Even small modifications in wording can make a big difference to the quality of a repayment relationship.
Most enterprise teams underestimated that effect initially.
They no longer do.
The rise of multilingual governance stacks
Another emerging pattern is the rise of what many CTOs informally call multilingual governance stacks.
These systems combine:
- AI-powered document translation
- Workflow orchestration
- Human review
- Compliance logging
- Access governance
- And analytics layers
The goal is not simply automation. It is operational defensibility at scale.
This matters because regulators increasingly expect institutions to explain not only what decision was made but also how communication surrounding that decision was handled.
In practice, this means enterprises need visibility into:
- Who approved a translated communication
- What source version was used
- Whether customer consent existed
- When changes were introduced
- And how escalation decisions evolved
That is difficult to achieve with fragmented tools.
Platforms focused on Indian language AI are increasingly being evaluated in this context — not just for translation capability, but for workflow-level orchestration across Indian languages and regulated enterprise environments.
The difference may sound subtle. Operationally, it is massive.
Why human oversight still matters in AI-driven compliance
There is a temptation in the market right now to over-automate everything.
That approach usually fails in regulated industries.
BFSI leaders have learned that language AI works best when paired with structured human governance instead of replacing it entirely.
The winning model is becoming clearer:
- AI handles scale
- Humans handle exceptions
- Governance systems handle accountability
This hybrid structure is particularly important for high-risk workflows such as:
- Legal notices
- Fraud investigations
- Insurance disputes
- Lending disclosures
- And ombudsman escalations
A fully autonomous system may accelerate throughput, but without review layers, it introduces governance risk.
Even Gartner's broader guidance around AI governance emphasizes that organizations failing to implement coherent governance frameworks will struggle to realize long-term AI value. (TechRadar)
In BFSI, that warning is particularly significant.
Because trust, once lost, is expensive to rebuild.
What the next phase looks like
Over the next three years, multilingual regulatory infrastructure will likely become as foundational as cybersecurity or cloud governance inside financial services.
Not flashy. Not consumer-visible. But essential.
Institutions will increasingly compete on:
- Speed of compliant servicing
- Audit readiness
- Multilingual operational consistency
- And customer trust across languages
The strongest organisations will not necessarily be the ones with the most AI pilots.
They will be the ones who operationalise governance at scale.
That includes:
- Unified document translation pipelines
- Regulator-ready auditability
- DPDP-aligned data practices
- Language-aware workflow intelligence
- And cross-channel consistency
The market is already moving there.
Quietly, but very fast.
And perhaps that is the most compelling part of this shift. Multilingual infrastructure in BFSI no longer primarily relies on inclusion mandates or digital expansion targets.
It is increasingly being driven by compliance economics.
That changes the conversation entirely.