The uncomfortable reality in 2026 is that most enterprises do not have an AI problem. They have a language execution problem.
For nearly two years, leadership conversations about generative AI have revolved around models—what to adopt, how to secure access, how to deploy copilots, and how to measure productivity. Yet the organizations that are quietly converting AI into revenue are not the ones running the most pilots. They are the ones who rebuilt their operating backbone around language.
That distinction sounds semantic until you sit inside a real customer workflow. Every meaningful enterprise interaction, acquisition, onboarding, servicing, compliance, retention, is mediated through text, voice, or documents. When those interactions break, it is not because the model is weak. They break because the system cannot understand, respond to, and act in the customer’s language with domain accuracy in real time.
McKinsey’s estimate that generative AI could unlock up to $4.4 trillion annually is often quoted for its scale, but the more revealing insight is where that value sits: customer operations, marketing and sales, software engineering, and R&D (Source). These are not model-heavy environments; they are language-heavy environments.
The companies that value languages have treated language as infrastructure.
Where the Early LLM Wave Fell Short?
If you map the first wave of deployments across large enterprises, a pattern appears. Productivity improved in isolated pockets. Internal content cycles accelerated. Support agents received drafting assistance. Knowledge retrieval became faster.
And yet, core business metrics, conversion velocity, activation rates, regulatory turnaround time, and multilingual market penetration moved far less than expected.
The reason is simple and rarely stated directly: most deployments stopped at the interface layer.
The model generated the answer, but the organization still relied on fragmented translation pipelines, manual document interpretation, English-first workflows, and channel-specific language handling. The intelligence never reached the transaction.
Deloitte’s long-running work on technology value repeatedly makes the same point in different forms: value is created when capability is embedded in the enterprise's operating fabric, not when it is layered on top of it (Source). Language is the fabric.
The Moment Language Became a Control Point
Something shifted when AI moved from experimentation to customer-facing execution.
A search query in Tamil is not a translation problem. It is a revenue event.
A voice-based onboarding journey is not a speech to text use case. It is an activation funnel.
A regulatory document in multiple languages is not a localization workflow. It is a compliance clock.
Once you see it this way, language stops being an output and becomes a control point inside the enterprise architecture. The system that governs how language is understood, generated, and audited begins to determine how fast the organization can grow.
This is particularly visible in markets where English has never been the dominant interface for digital adoption. High-accuracy English to Tamil translation inside a live commerce flow does not improve communication in a generic sense; it changes search behavior, reduces drop-offs, and increases transaction completion. The effect shows up in revenue dashboards, not in content metrics.
From Tools to an Operating Layer
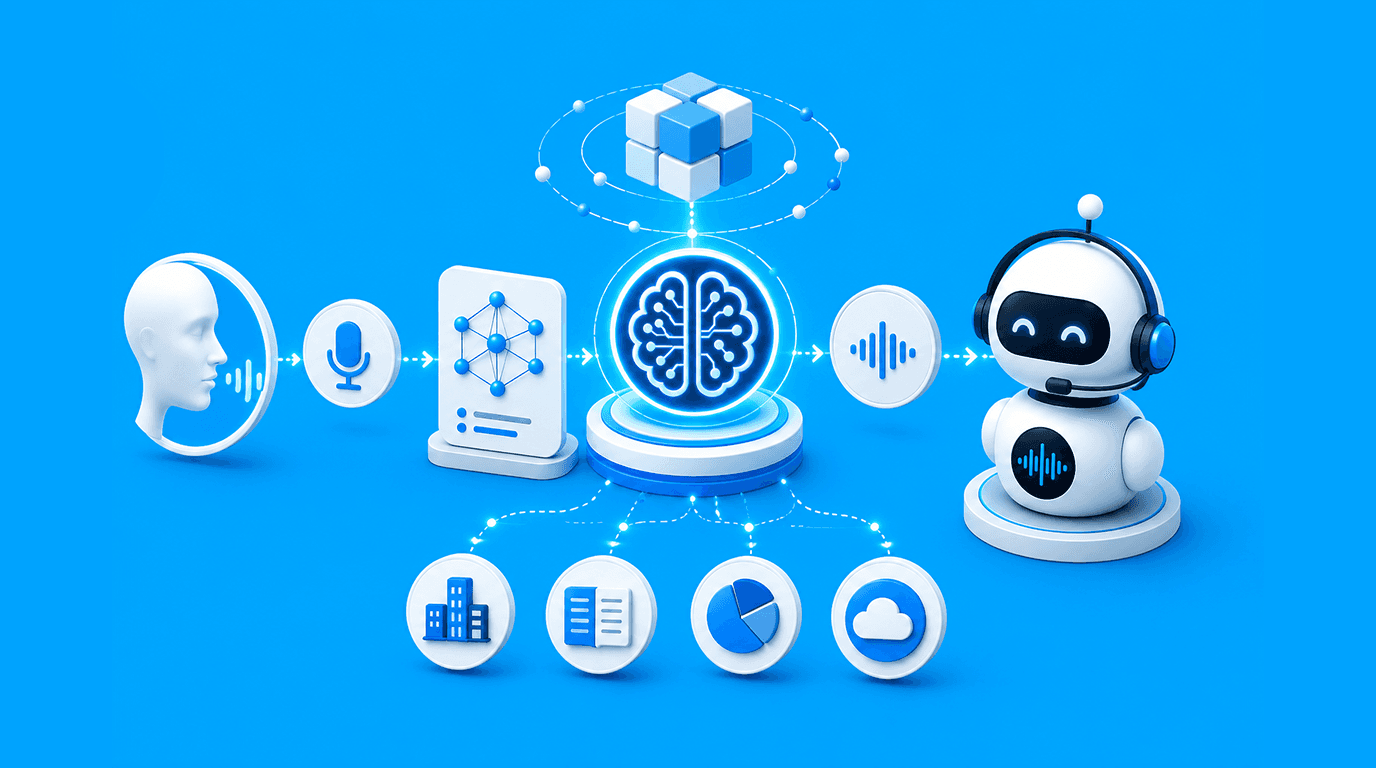
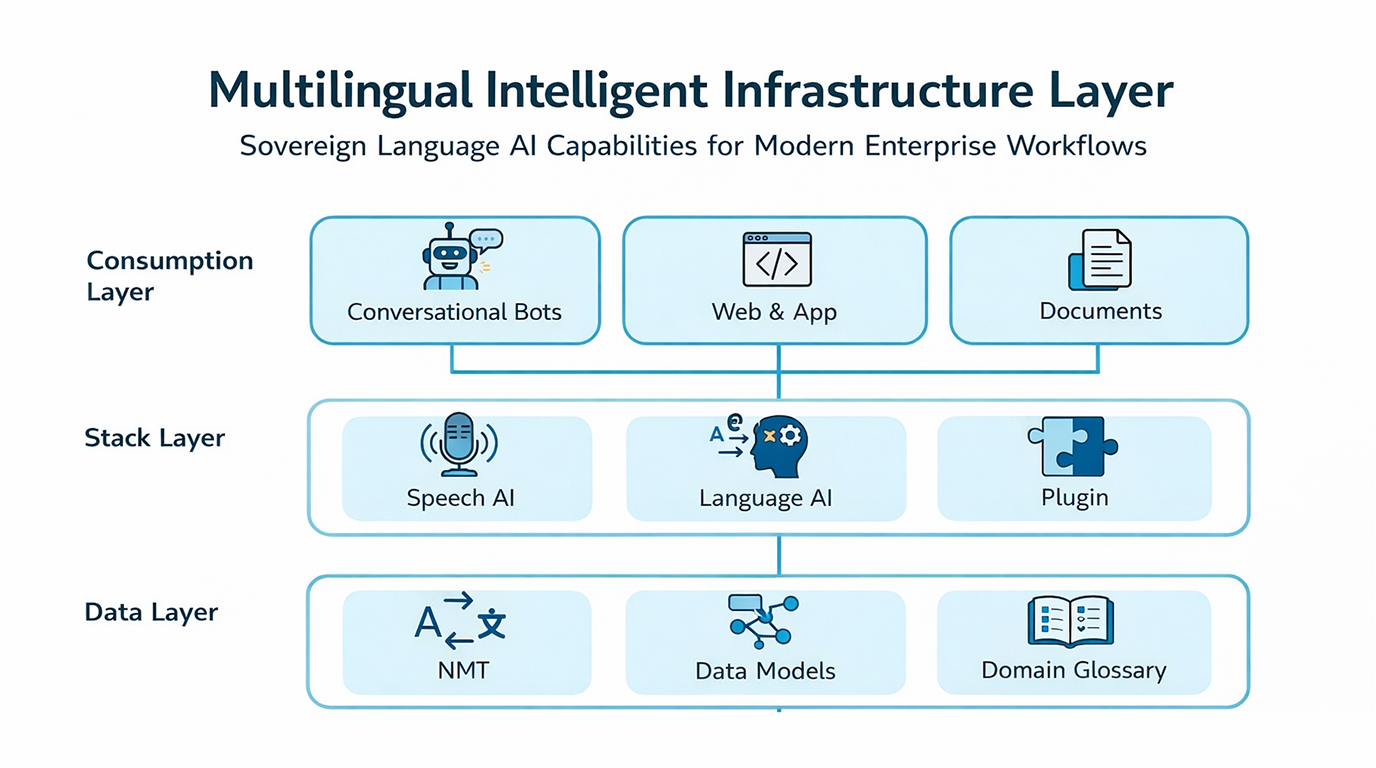
The language layer now emerging within forward-moving enterprises has very little in common with traditional localization stacks. It behaves more like a real-time orchestration system.
- It sits between the model and the workflow.
- It understands domain context.
- It maintains consistency across channels.
- It produces auditable outputs.
- It learns from interaction data.
Once this layer is in place, the same model suddenly begins to produce radically different business results, because its outputs are no longer generic text; they are executable actions inside the enterprise system.
Harvard Business Review recently framed the broader pattern in a way that applies directly here: companies that capture disproportionate value from new technologies redesign their core processes around them, while others simply automate existing steps.
Language AI infrastructure is that redesign.
Why This Is Playing Out Faster in India
India is often described as a multilingual market, but that description understates what is actually happening. It is the first large-scale digital economy where language determines whether a user participates in the formal system at all.
That creates a very different set of architectural requirements. The enterprise cannot treat language as a post-event activity, because the transaction itself depends on it.
This is why a new category of platforms, Devnagri among them, is positioning itself not as a translation vendor but as an embedded language intelligence layer that operates across onboarding journeys, support environments, document workflows, and discovery systems. The shift in positioning reflects a deeper change in how value is created: infrastructure compounds, services do not.
The Financial Logic Behind the Shift
When language is embedded into the operating model, four economic effects tend to appear simultaneously.
Customer acquisition becomes more efficient because discovery happens in the user’s natural language rather than through forced linguistic behavior. Activation cycles shorten because forms, documents, and assisted journeys are understood the first time. Cost-to-serve declines as automation becomes viable in voice and chat interactions that were previously too complex. Regulatory processes accelerate because multilingual communication becomes standardized and traceable.
None of these outcomes requires a new model. They require a new system.
The Risk of Staying Model-Centric
Many organizations are still investing primarily in model access and prompt engineering capability. That strategy is beginning to show its limits.
Models are rapidly commoditizing. Accuracy differences are narrowing. Access is no longer a durable advantage.
What does not commoditize is the infrastructure that connects those models to proprietary workflows, domain data, and real customer interactions across languages.
Enterprises that delay building this layer are not standing still; they are accumulating structural friction that becomes visible in slower expansion, inconsistent customer experience, and underperforming AI investments.
What Businesses Need to Reframe
The most important shift for leadership is conceptual.
Language should no longer be measured in terms of volume processed or content produced. It should be measured by business outcomes: conversion rates across regions, activation speed, resolution time, and compliance turnaround.
The second shift is architectural. A fragmented vendor landscape cannot produce a unified language experience, and without a unified experience, the data never compounds.
The third shift is governance. In regulated industries, language errors are not brand issues; they are legal and financial risks. Infrastructure is what makes linguistic accuracy auditable.
Closing Perspective
The first phase of generative AI created a race for capability. The second phase is creating a race for execution.
Execution, in a digital economy, happens through language.
The enterprises that recognize this early are not simply improving communication. They are redesigning how revenue moves through their systems. And once that redesign is complete, every new model they adopt compounds faster than it does for everyone else.
The advantage will not belong to those who deploy AI everywhere. It will belong to those who make it work everywhere people speak.